

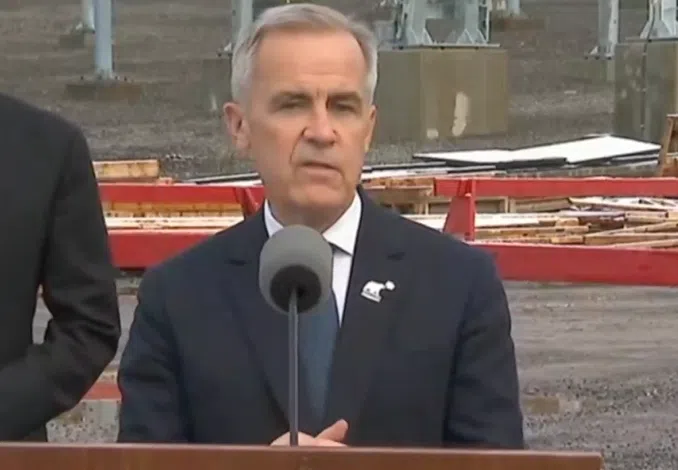
PM Mark Carney speaks in Terrace BC
TORONTO — Canada’s major banks are committing hundreds of billions of dollars in new financing that includes energy, critical minerals and infrastructure, potentially giving Alberta’s oil and gas sector access to a significantly larger pool of investment capital.
The commitments were announced at the first Canada Investment Summit, which the federal government says generated nearly $500 billion in new investment commitments across the country.
TD Bank is committing $150 billion in financing over five years across sectors including energy, critical minerals and resources, defence and aerospace, digital and artificial intelligence, and infrastructure.
BMO says it will invest and mobilize $70 billion over 10 years in critical Canadian sectors, including energy and transportation infrastructure, mining and critical minerals, AI computing, defence and security.
Scotiabank is also committing more than $100 billion in financing over five years to support Canadian companies and projects in sectors expected to drive economic growth, while CIBC is providing $2 billion in financing to defence-related and dual-use businesses operating in strategic sectors that include energy and infrastructure.
Sun Life Financial is committing another $5 billion over five years to critical infrastructure, including energy and transportation.
Power Sustainable says it will invest and mobilize more than $10 billion for Canadian infrastructure, including power and grid projects.
Prime Minister Mark Carney also used the summit to announce the Productivity Mega Deduction, which expands the range of capital investments businesses can immediately deduct.
The measure specifically includes oil and gas pipelines and mining property, along with fibre-optic cable, software, research and development, computer equipment, aircraft, vehicles, rail track, bridges and roads.
Ottawa says the change will lower Canada’s marginal effective tax rate on new business investment from about 13 per cent to 6.4 per cent.
The federal government is framing the summit as part of a broader push to attract capital into energy, critical minerals, infrastructure and technology.
Investors from nearly 30 countries attended the summit, representing institutions managing more than $100 trillion in assets.
The government says the agreements are expected to direct investment into Canadian businesses and industries including energy and critical minerals.
While the scale of the financing commitments could create new opportunities for Alberta’s energy sector, the summit announcement does not identify a specific Alberta oilsands, pipeline, natural gas or power project receiving funding.

Comments